Home / Insights / Financial Awareness
Srinivas Kambhampati — AMFI Registered Mutual Fund Distributor (ARN-265474), EUIN E091320
Why the Relationship Between Source and Destination Funds Matters
Moving money systematically between mutual fund schemes requires evaluating both the starting source fund and the ending destination fund. Here is how their relationship shapes your transfer strategy.
When managing capital, investors often look for structured ways to transition money from one asset class to another over time. A common method is deploying a Systematic Transfer Plan, where a fixed amount or variable unit is periodically shifted out of a source fund and into a destination fund. While the concept sounds straightforward, treating the source and destination as independent units can lead to operational friction and unintended financial outcomes.
The two schemes selected for a transfer strategy do not operate in isolation. Their structural relationship, asset classifications, tax treatments, and underlying risk profiles directly govern how effectively your capital shifts across time. Understanding how these two funds interact helps investors design systematic transfer strategies that reflect their broader household goals.
1. Operational Mandates: The Fund House Requirement
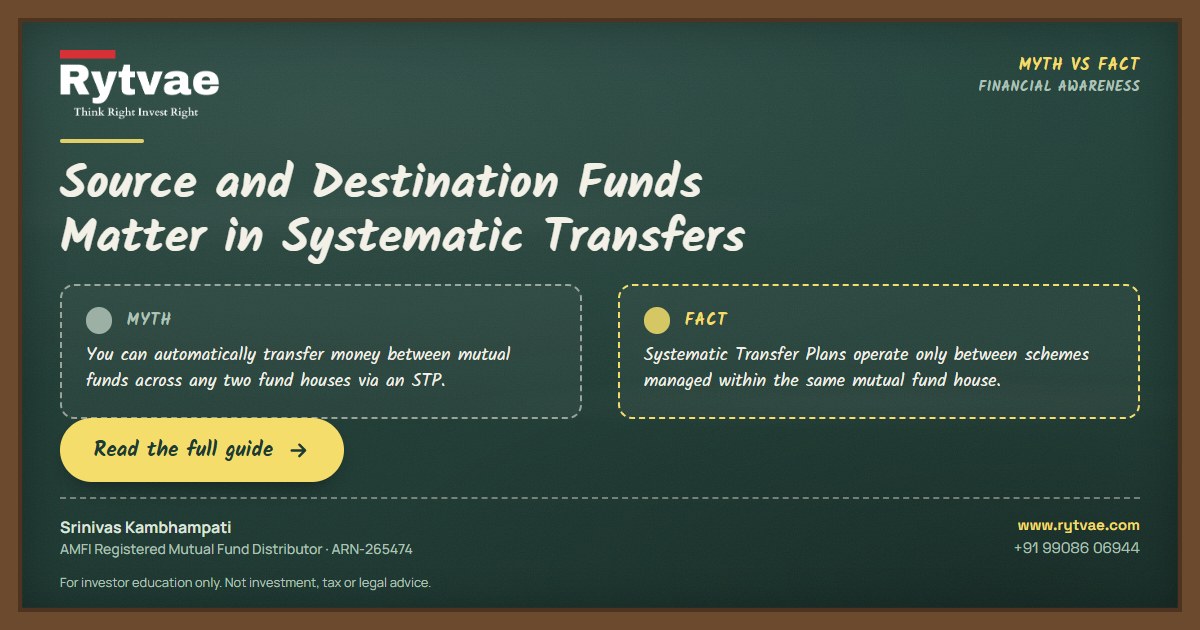
The primary operational rule governing a Systematic Transfer Plan is that both the source fund and the destination fund must belong to the same mutual fund house or Asset Management Company. You cannot set up a standard automated transfer from a scheme managed by one fund house directly into a scheme managed by a completely separate fund house.
Because the transaction relies on internal account mechanics, the scheme offerings of a single fund house limit the universe of available source-destination pairings. If an investor holds capital in a liquid fund of one institution but prefers an equity scheme offered by another, a direct systematic transfer cannot be registered. Instead, manual redemption and reinvestment workflows must be used, or capital must first be placed within an eligible source fund of the target fund house.
2. Mechanistic Reality: Redemptions and Purchases
A frequent point of confusion is the belief that a transfer between source and destination funds is merely a balance adjustment within an account. Mechanically, every instalment of a systematic transfer consists of two distinct transactions executed simultaneously: a redemption of units from the source fund and a purchase of units in the destination fund.
Because the source transaction is a redemption, it triggers a tax event under Indian tax laws. The gain or loss realized on units redeemed from the source scheme is evaluated based on the holding period of those specific units. Equity-oriented source funds and non-equity source funds face different tax holding periods and capital gains tax rules. Consequently, the choice of source fund directly dictates the tax implications of every periodic transfer instalment, regardless of what destination fund is chosen.
3. Risk Balancing and Asset Allocation Profile
The core objective of using a source and destination mechanism is often to manage volatility while entering or exiting specific asset classes. The risk profile of the source fund serves as the anchor, while the destination fund represents the target allocation.
For instance, placing capital into a low-volatility source fund such as a liquid or overnight scheme allows the uninvested balance to maintain relative capital preservation while small tranches move into an equity destination fund over time. Conversely, transferring from an equity source fund into a debt destination fund reverses this balance, systematically reducing equity exposure. Evaluating the risk attributes of both funds ensures that the overall portfolio risk shifts gradually without introducing unintended volatility during the transition period.
4. Liquidity Needs and Minimum Transaction Thresholds
Mutual fund schemes specify minimum transaction amounts and frequency rules for systematic transfers. Furthermore, the liquidity profile of the source fund dictates whether capital is consistently available to fulfill scheduled transfers without exit loads or liquidity delays.
If a source fund imposes an exit load on units redeemed before a specified duration, systematic transfers initiated shortly after a lump sum deposit could incur exit loads on early instalments. Investors reviewing prospective pairings should check scheme offer documents to confirm that the source fund exit load window and minimum transfer amounts align with their intended transfer frequency and duration. To explore how automated transactions interact with long-term financial planning, you can read about comprehensive Financial Planning Services in Bangalore or test prospective projections using Financial Calculators.
5. Aligning Fund Pairings with Financial Goals
Selecting appropriate source and destination funds requires stepping back to examine the overarching financial objective. Whether preparing for a child's higher education expenses or structuring post-retirement cash flows, the duration of the transfer plan should mirror the time horizon of the specific goal.
For structured goal management, reviewing overall portfolio structures through dedicated solutions like Our Services can provide clarity on scheme selection rules. When you are ready to evaluate your existing holdings or discuss structured allocation frameworks, you can reach out via Contact Rytvae Consulting to discuss your requirements with Srinivas Kambhampati, AMFI Registered Mutual Fund Distributor.
Frequently asked questions
Can I set up an automated transfer between mutual funds from two different fund houses?
No, standard systematic transfer plans can only be registered between schemes managed by the same mutual fund house. If you wish to move money between different fund houses, you must manually redeem capital from one fund, transfer the proceeds to your bank account, and then invest in the destination fund.
Is a transfer from a source fund to a destination fund tax-free?
No, transferring capital out of a source fund is classified as a redemption under Indian tax laws. Capital gains tax applies based on the type of source fund, holding period, and applicable tax regulations at the time of each transfer instalment.
What happens if the source fund does not have sufficient balance for an instalment?
If the source fund balance falls below the scheduled transfer amount or the minimum scheme threshold, the specific transfer instalment will fail or the systematic transfer plan may be discontinued according to the fund house rules.
Srinivas Kambhampati — AMFI Registered Mutual Fund Distributor (ARN-265474), EUIN E091320. This material is published for general investor education and awareness. It is not investment advice, tax advice or legal advice, and it does not take account of any individual's objectives or circumstances. Please consult an appropriately qualified professional before acting. Rytvae Consulting is not a SEBI-registered investment adviser.
See our full disclosures and disclaimers.